House Panel Holds Billionaire Leon Black in Contempt Over Epstein 📸 Image Credit: usatoday.com By Azeem-USA · Wed Sep 16 2026 English (en-US) In a significant move that underscores the growing pressure for transparency in Washington, a key House panel has taken decisive action against one of the world's wealthiest individuals. The decision to hold billionaire investor Leon Black in contempt marks a turning point in the ongoing investigation into how law enforcement handled the Jeffrey Epstein case. In this analysis, we dive into the details of the vote, the historical relationship between Black and Epstein, and what this development means for the future of federal oversight and legal accountability. 📑 Table of Contents The Unanimous Vote Against Leon Black Who is Leon Black and Why the Epstein Connection? Chairman James Comer's Stance on Accountability The Legal Implications of Contempt Congress The Impact on the Jeffrey Epstein Investig...
🚨 Breaking News Analysis
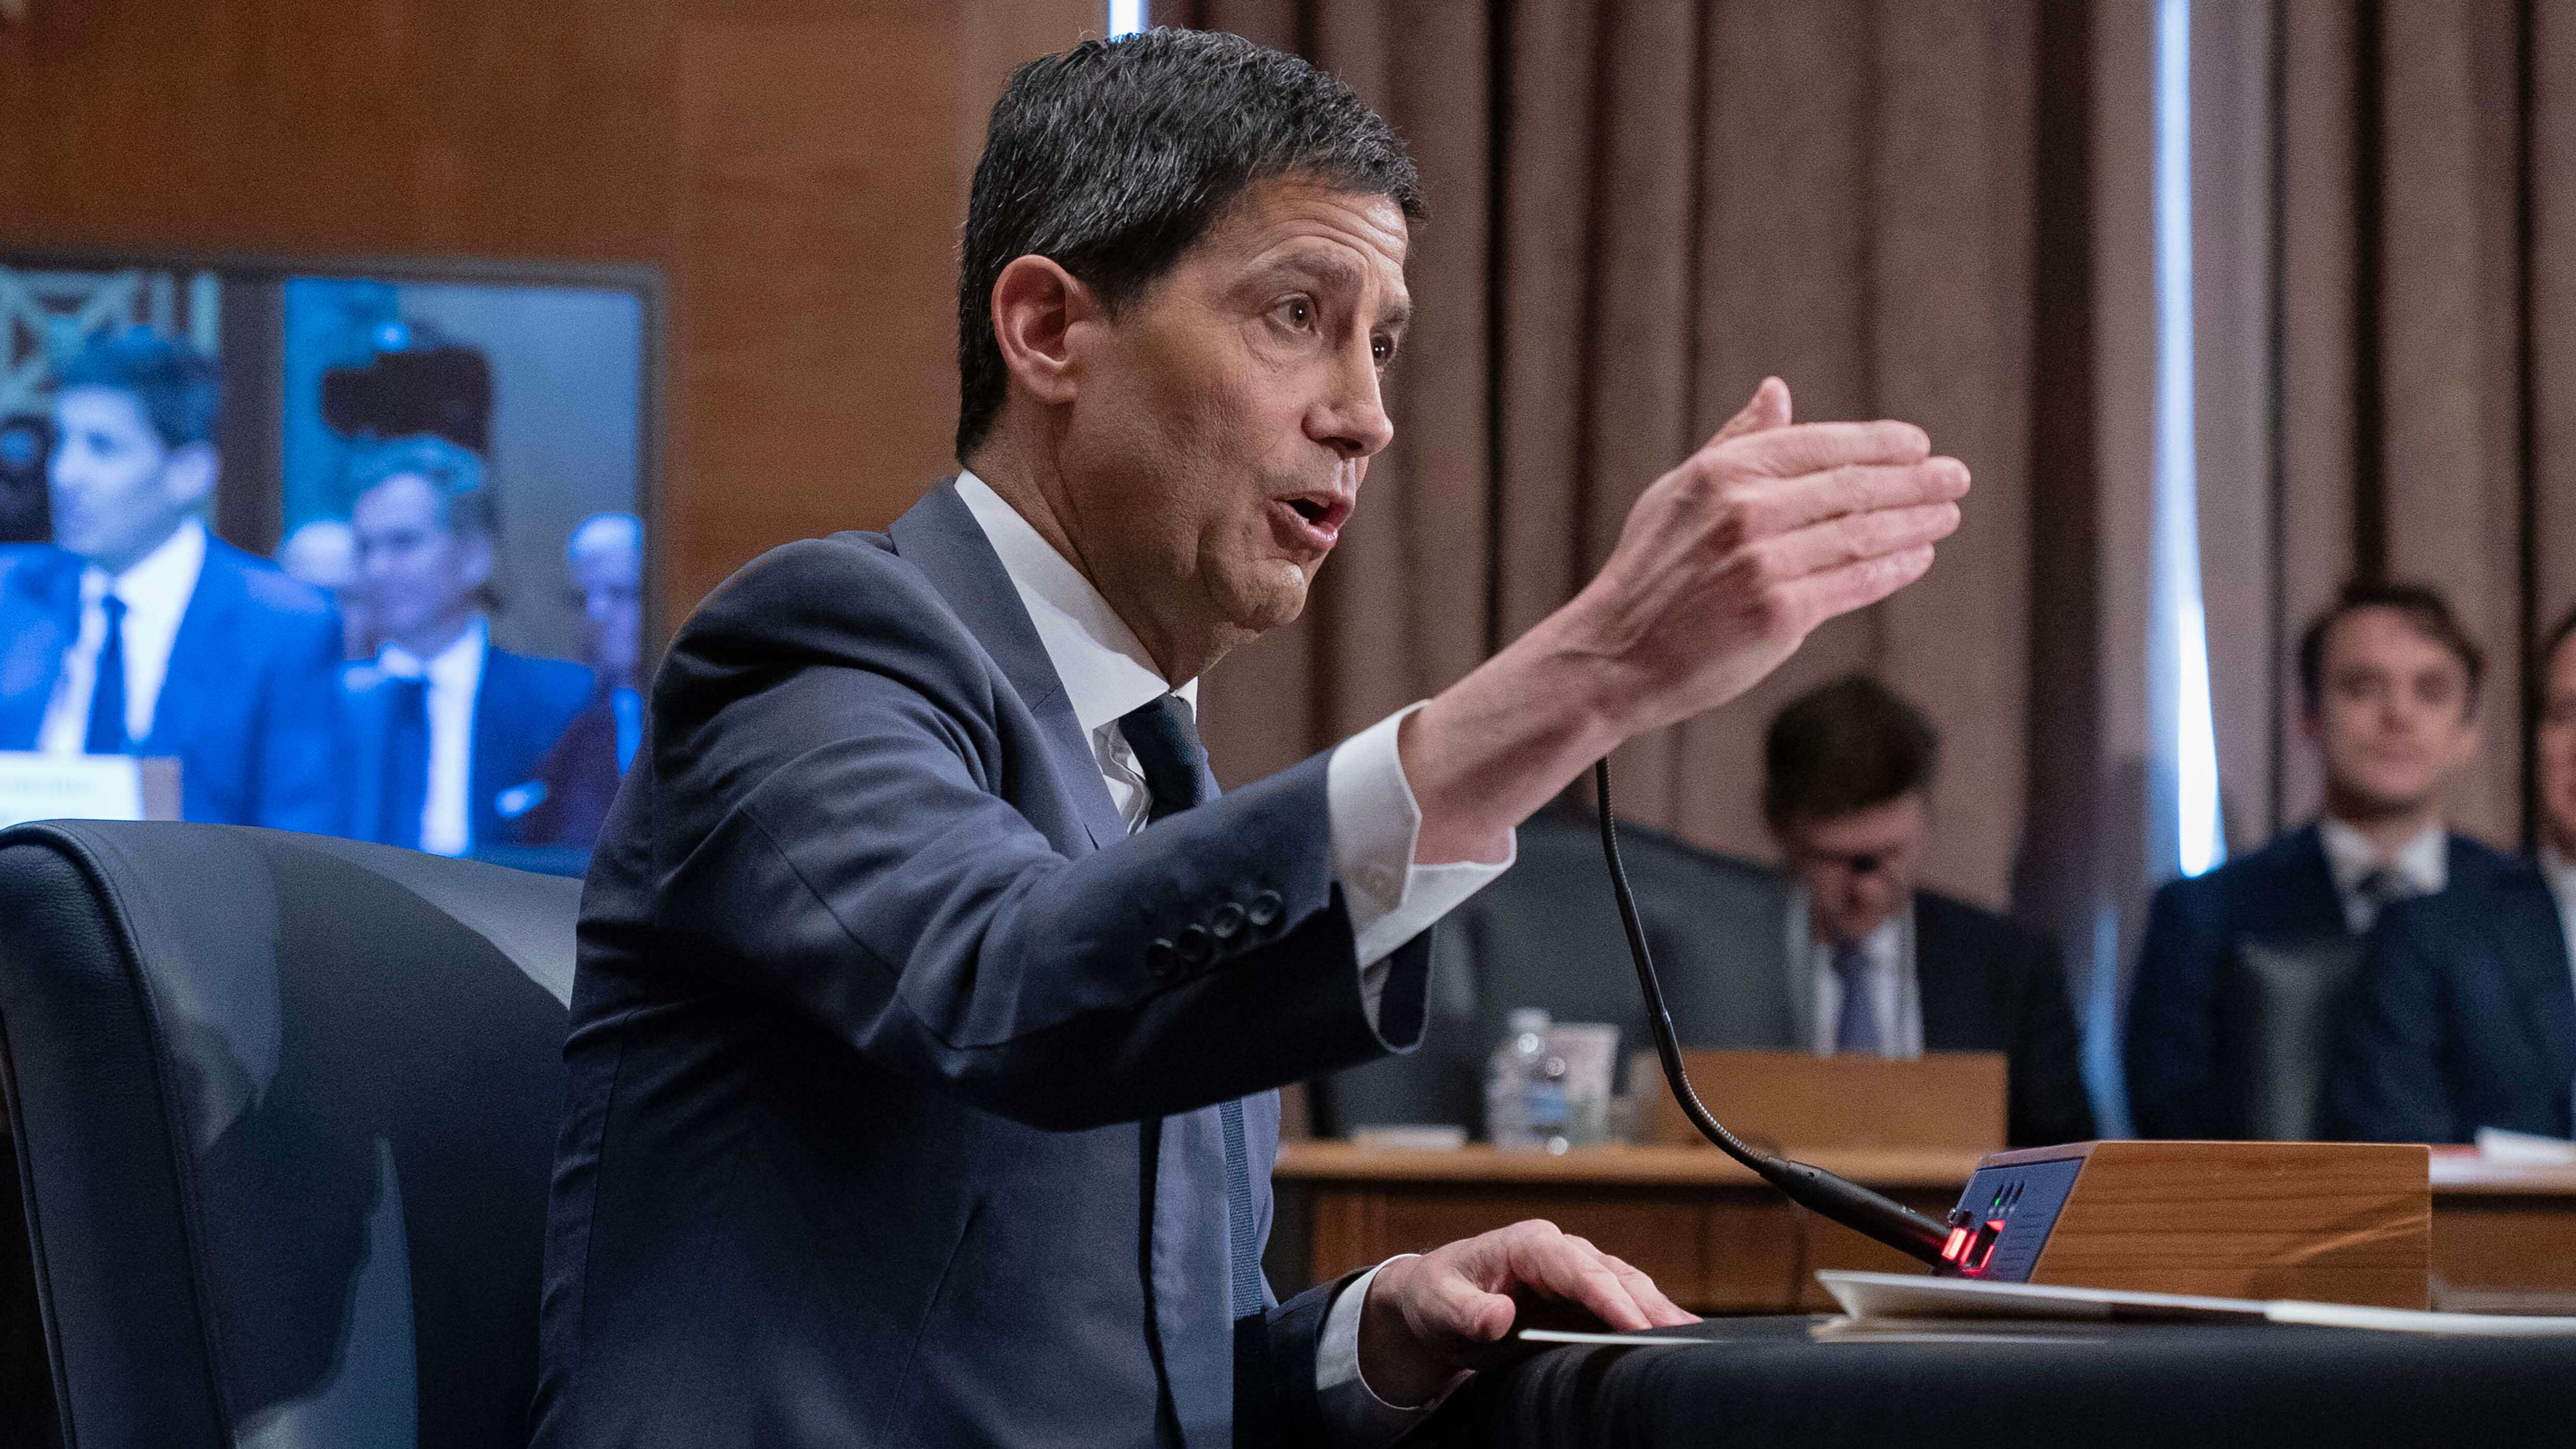
The Federal Reserve has officially raised its benchmark interest rate for the first time in over three years, a move signaling a significant shift in monetary policy. This decision, announced Wednesday, will reverberate through personal finances, making borrowing more expensive while offering a glimmer of hope for savers.
This analysis breaks down the immediate implications for your bank accounts, loan obligations, and credit card balances, providing critical context in a rapidly evolving economic landscape.
📑 Table of Contents
1. The Fed Delivers the Expected Hike
The Federal Reserve's Federal Open Market Committee (FOMC) concluded its policy meeting Wednesday by announcing a widely anticipated quarter-percentage-point increase to its target for the federal funds rate. This marks the first such hike since December 2018, ending an extended period of near-zero interest rates. The move is a direct response to persistent inflationary pressures and a robust labor market.
Fed Chairman Kevin Warsh, speaking after the announcement, indicated that further rate increases are likely on the horizon. The committee's projections, often referred to as the 'dot plot,' suggest multiple hikes are planned throughout the year. This forward guidance aims to manage market expectations and signal the Fed's commitment to its inflation-fighting mandate.
Market Reaction and Expectations
While the rate hike itself was largely priced in by financial markets, the accompanying statements and projections from the Fed are crucial. Analysts will be scrutinizing every word for clues about the pace and magnitude of future tightening. Early market reactions, though often volatile, suggest a cautious optimism, with some expecting the Fed to navigate this transition effectively.
2. Impact on Your Savings Accounts
For millions of Americans with money sitting in savings accounts, this rate hike offers a much-needed, albeit modest, reprieve. As the federal funds rate increases, banks typically follow suit by raising the Annual Percentage Yield (APY) on savings accounts, money market accounts, and certificates of deposit (CDs). This means your deposited funds will begin to earn slightly more interest.
However, the boost for savers is likely to be gradual and may not immediately keep pace with inflation. For years, savings rates have been at historic lows, meaning even a quarter-point increase translates to pennies on larger balances. Savers should actively compare rates from different institutions, as online banks and credit unions often offer more competitive yields than traditional brick-and-mortar banks.
The Role of Inflation
The primary driver for this rate hike is elevated inflation. While savers will see a small increase in their earnings, the real return on savings—interest earned minus inflation—may still be negative. The Fed's goal is to curb inflation, which erodes purchasing power. A higher savings rate is a positive development, but it's part of a larger strategy to stabilize the economy.
3. Borrowing Costs Set to Climb
The most immediate and widely felt consequence of a Fed rate hike is the increased cost of borrowing. The federal funds rate serves as a benchmark for many other short-term interest rates. Consequently, consumers can expect to see higher rates on variable-rate loans, including adjustable-rate mortgages (ARMs), home equity lines of credit (HELOCs), auto loans, and personal loans.
For individuals with significant debt tied to these variable rates, this means monthly payments will likely increase. This added cost can strain household budgets, particularly for those already managing tight finances. Homeowners with ARMs should brace for potential payment adjustments, and prospective homebuyers may find mortgage rates ticking upward, impacting affordability.
Fixed-Rate Loans and Mortgages
While variable-rate products are directly affected, fixed-rate loans and mortgages can also see indirect impacts. Lenders often adjust their pricing for new fixed-rate products in anticipation of future Fed actions and broader market conditions. Therefore, individuals looking to secure a new fixed-rate mortgage or auto loan might encounter slightly higher rates than they would have before the Fed's announcement.
4. Credit Cards: A Double-Edged Sword
For credit card holders, the Fed's rate hike presents a mixed bag. Most credit cards carry variable Annual Percentage Rates (APRs) that are directly linked to the prime rate, which in turn is influenced by the federal funds rate. As the Fed raises rates, the prime rate typically increases by the same amount, leading to a higher APR on your credit card balances.
This means that carrying a balance on your credit cards will become more expensive. Interest charges will accumulate faster, making it harder to pay down debt. Consumers who regularly pay off their balances in full each month will likely feel little to no direct impact on their interest costs. However, those who carry balances, even for a short period, will see their interest expenses rise immediately.
The Risk of Increased Debt Burden
The increased cost of carrying credit card debt is a significant concern. As borrowing becomes more expensive across the board, consumers may rely more heavily on credit cards for short-term financing. This, combined with rising interest rates on those cards, could exacerbate debt burdens for vulnerable households. Financial advisors urge consumers to review their credit card statements and consider strategies to reduce balances or transfer them to cards with lower introductory rates, if possible.
5. The Bigger Picture and What's Next
This rate hike is not an isolated event but rather the beginning of a monetary policy normalization cycle. The Fed is acting to combat inflation, which has reached levels not seen in decades. By increasing borrowing costs, the central bank aims to cool demand, slow down economic activity moderately, and bring price increases back towards its target of around 2%.
The implications extend beyond individual finances. Higher interest rates can affect business investment, stock market valuations, and the overall pace of economic growth. The Fed faces a delicate balancing act: tightening policy enough to curb inflation without tipping the economy into a recession. Market participants will be closely watching upcoming economic data—particularly inflation reports and employment figures—for clues on the Fed's next moves.
Navigating the New Environment
For consumers, the key takeaway is to adapt to a higher-interest-rate environment. This means re-evaluating debt, prioritizing paying down high-interest balances, and potentially seeking out better rates on savings. Understanding how these shifts impact your personal financial plan is crucial for making informed decisions in the months ahead.
🔥 Follow Azeem USA for continuous breaking news analysis and updates on economic shifts.
Conclusion
The Federal Reserve's decision to raise interest rates marks a pivotal moment, signaling a shift away from the era of ultra-low borrowing costs. This move directly impacts the cost of loans and credit card debt, while offering a modest improvement for savers. The Fed's commitment to tackling inflation suggests further rate increases are probable.
As the economic landscape recalibrates, individuals must stay informed and adjust their financial strategies. Monitoring inflation trends, interest rate decisions, and economic indicators will be paramount for navigating the coming months successfully.
❓ FAQ
When was the last Fed rate hike before this one?
The last Federal Reserve rate hike occurred in December 2018.
Will my savings account interest rate increase immediately?
Interest rates on savings accounts typically increase following a Fed hike, but the rise may be gradual and vary by bank.
How will this affect my mortgage payment?
Adjustable-rate mortgages (ARMs) are most likely to see immediate increases. Fixed-rate mortgages may see slightly higher rates for new applications.
What is the Fed's main goal with raising rates?
The primary goal is to combat high inflation by slowing down demand and economic activity.
Should I pay off my credit card debt now?
With rates likely to rise, paying down high-interest credit card debt is strongly advised to minimize future interest costs.
Comments
Post a Comment